Quick answer: The most useful money habits for college students in 2026 are tracking expenses, telling needs apart from wants, building a small emergency fund, picking up a flexible side hustle, using student discounts, using credit cards carefully, and starting to invest early, even with small amounts. You don’t need a finance degree for any of this. You need actually to do it for more than two weeks.
If you’re a college student trying to figure out why your bank account keeps hitting zero before the semester ends, this is for you.
My first semester away from home, I had a checking account, a debit card, and zero idea what I was doing. Nobody hands you a manual for this. I remember being weirdly proud of myself for meal-prepping chicken and rice for a week straight, and then three days later standing at the campus coffee shop confused about why my card got declined for a $4 latte. Turns out meal-prepping doesn’t help much if you’re still dropping $28 a week on coffee without noticing.
personal finance money management guide’
That’s basically the whole point of this article.
College isn’t just where you pick a major. It’s where you build the money habits you’ll carry for the next twenty years, whether you mean to or not. And with how much rent and groceries cost in 2026, “I’ll figure it out later” stopped being a real plan a while ago.
Seven habits, explained without jargon. Pick one and start.
A quick note on why this matters more now
A few years back, joking about eating instant noodles was mostly just a joke. For a lot of students, it’s closer to an actual budgeting constraint these days since prices have gone up on nearly everything. On the flip side, there are more flexible ways to earn a bit of extra money than there used to be — freelance apps, tutoring platforms, fractional investing accounts. None of that really existed for the average student a decade ago.
Higher costs, easier ways to earn on the side. That combination is exactly why starting these habits early matters more than people think.
1. Track every dollar, including the small stuff
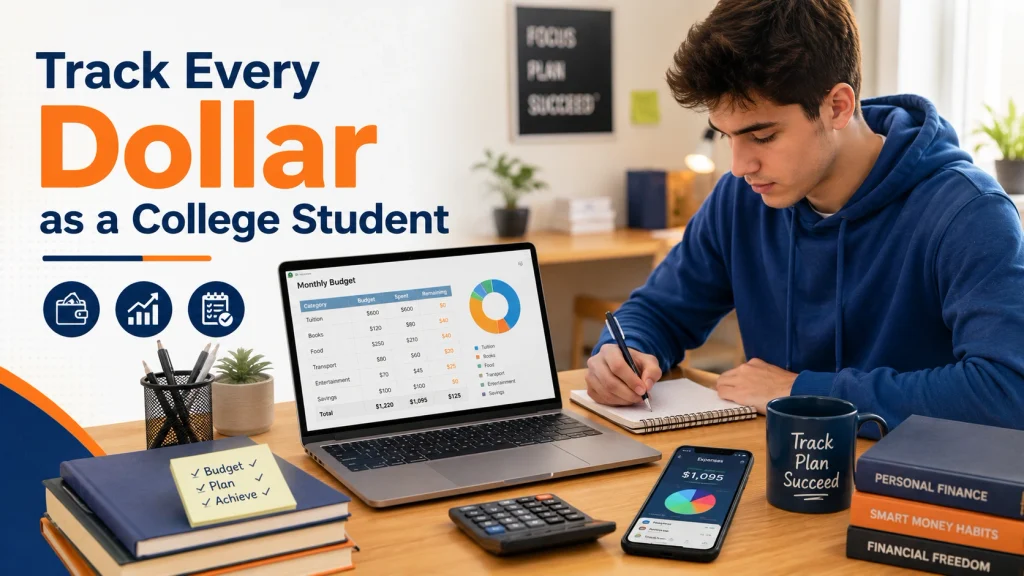
You can’t fix a leak you can’t see. Most students have no real idea where their money goes because it rarely disappears in one big purchase. It leaks out five bucks at a time.
Quick test — can you say off the top of your head how much you spent on delivery food last week? Most people can’t.
For 30 days, write down every transaction. The $2,000 tuition payment and the $1.50 vending machine snack both go in the log. Use a free app, your phone’s notes, a paper notebook- doesn’t matter. What matters is actually seeing the pattern show up.
Once you notice four coffee runs a week at $6 each, it stops feeling abstract. That’s $96 a month. Over a year, it’s more than a thousand dollars on coffee alone. Maybe that’s fine with you. Maybe it isn’t. Either way, it’s now a choice you’re making with your eyes open instead of one that happens to you.
2. Learn to tell needs apart from wants
Campus life runs on a kind of peer pressure that doesn’t always look like peer pressure. Someone’s always ordering delivery on a random Thursday. A friend just got a new phone. Your group chat is planning a trip that costs more than your rent.
None of that is a problem on its own. It becomes one when you can’t tell the difference between what keeps you afloat and what’s just nice to have.
Rent, groceries, required textbooks, getting to class, and honestly phone and internet too — those are needs at this point. Food delivery, concert tickets, an extra streaming subscription, new clothes, a night out — those sit in the want column.
You don’t have to cut out every want. College should still be fun. The real skill is pausing for two seconds before checkout and asking whether you need this to get through the week or want it right now. Ask that enough times and a lot of the financial stress fades on its own.
3. Build a small emergency fund, even just $500
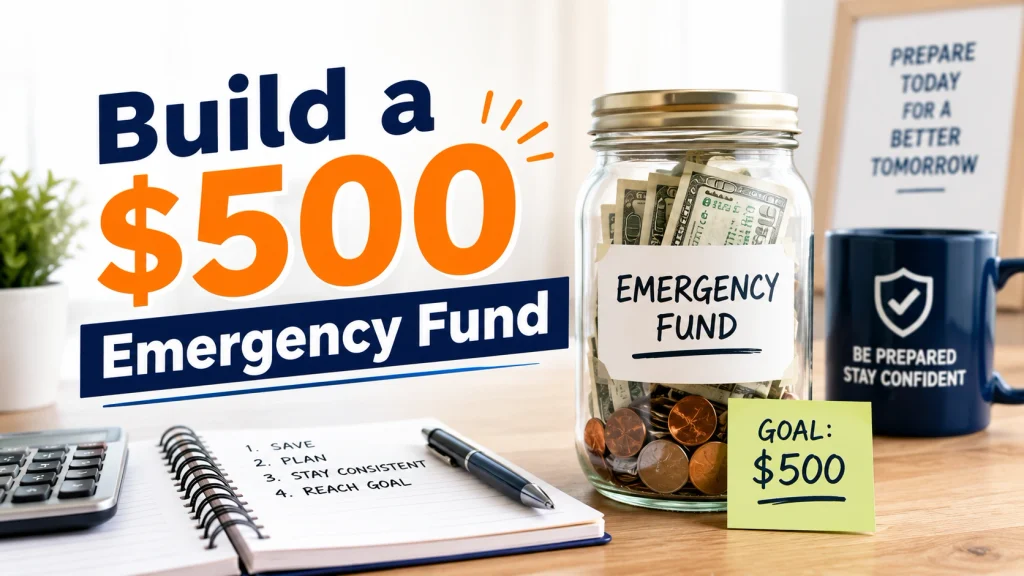
Life doesn’t check your class schedule before something goes wrong. A cracked phone screen. A copay you didn’t see coming. A flight home because something happened with family. If you’ve got zero savings, a bad week turns into a real crisis fast.
That’s what an emergency fund is for. You don’t need thousands sitting around — $500 is a realistic starting point and covers most common student emergencies without much drama.
Save $15 a week, and you’re at $780 in a year. Push it to $25, and you hit $1,300. Even $10 a week gets you past $500 in under twelve months.
Put it in a separate savings account, not your everyday checking. If it’s too easy to reach, you’ll spend it on something that isn’t actually an emergency. We’ve all done it. Out of sight, mostly out of reach, but there the one time you actually need it.
4. Pick up a side hustle that works around your schedule
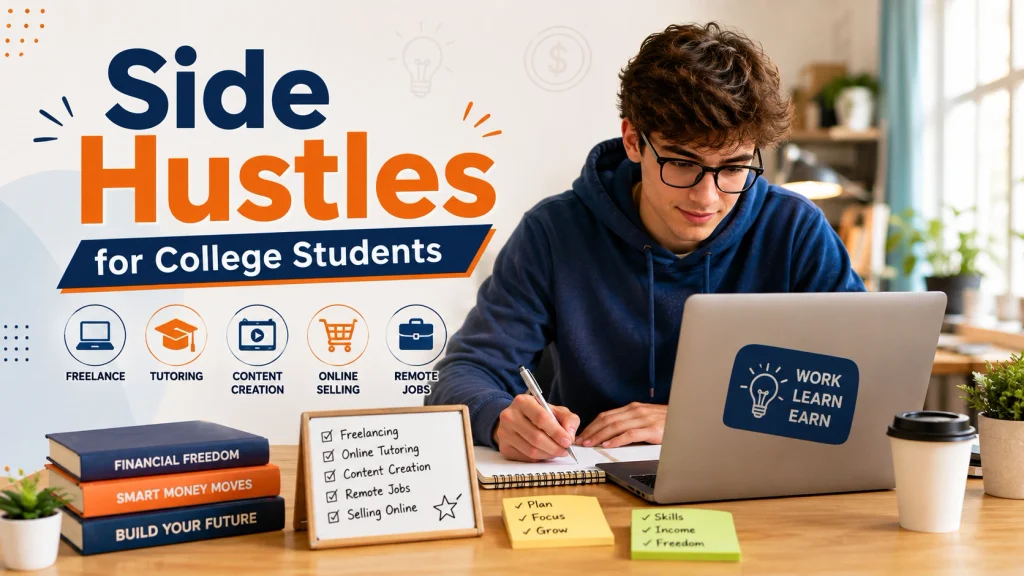
“Working through college” used to mean a rigid retail shift that fought with your class times. That’s changed. The gig economy in 2026 makes it possible to earn money around your classes instead of replacing them.
Think about what you’re already decent at. Good with design or social media — there’s freelance work for that. Strong writer or a careful editor — small businesses and even classmates will pay for proofreading and editing. Ace a subject — peer tutoring, in person or online, pays better than people expect. Comfortable on camera or with a mic — short-form content and voice work are both growing fast.
An extra $50 to $100 a week changes things more than it sounds. Breathing room in your budget, a faster-growing emergency fund, less panic during midterms when money’s tight.
5. Get smart about textbooks and student discounts
Your campus bookstore is not trying to save you money. Walking in and buying new textbooks at full price is one of the easiest expenses to avoid, and many first-year students still do it anyway.
Before buying new, check the campus library first — a surprising number of required texts are on reserve. Then digital rentals through Amazon or Chegg. Then used copies from someone who already took the class. Sometimes there’s even a free PDF for intro-level courses if you look.
Your student ID is basically a discount card most people forget they’re carrying. Streaming, software, clothing, sometimes even restaurants — a lot of places knock something off for students, but you have to ask. Get in the habit of checking before you pay for anything, and 10 to 15 per cent savings adds up to real money over four years.
6. Treat credit cards like a tool, not free money
Credit card companies show up on campuses hard for a reason. They know students who sign up early tend to stick with that card for years, sometimes at real cost.
Used right, a credit card builds the credit history you’ll need later for an apartment, a car, eventually a mortgage. Used carelessly, it’s one of the more expensive mistakes you can make in your twenties.
One rule matters here: don’t charge anything you couldn’t pay off in cash right now. Carry a balance, and interest starts stacking fast — a $60 purchase can turn into $150 before you notice.
If you’re not sure you can stick to that yet, there’s no shame in a debit card for now. Credit can wait a semester. Digging out of high-interest debt takes a lot longer than that.
how to raise your credit score fast’
7. Start investing, even in small amounts
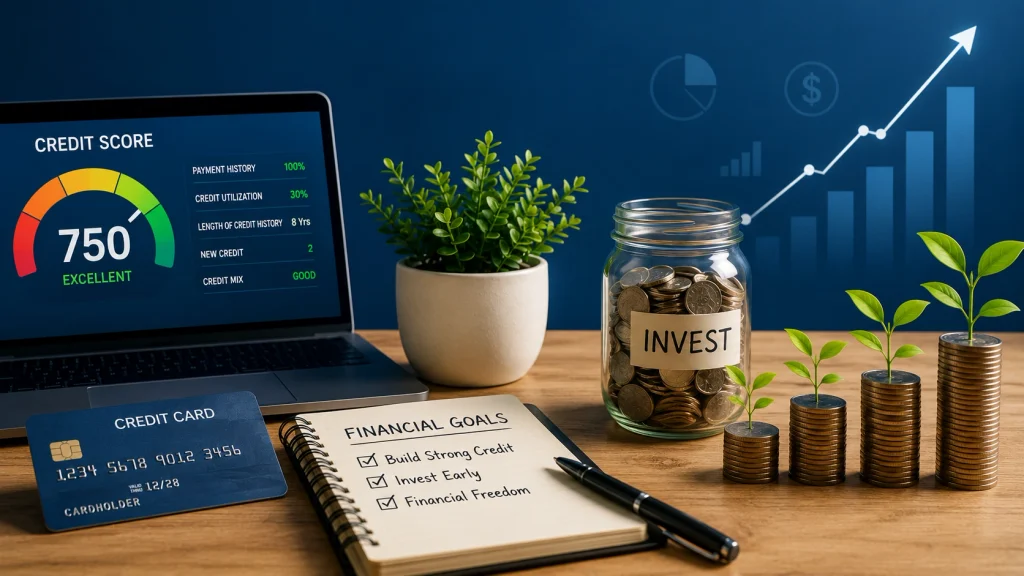
Many students assume investing is for later, once they have a real job and a few thousand dollars sitting around. That thinking gives up your one real advantage right now — time.
Money invested at 19 has decades longer to grow than the same amount invested at 30, thanks to compound growth. You don’t need to pick winning stocks or time anything to benefit from that. You need to start.
Most investing apps in 2026 let you begin with $5 through fractional shares. Rather than chasing whatever stock or crypto is trending that week, most financial educators point beginners toward diversified index funds or ETFs, which spread your money across a lot of companies instead of one.
Ten or twenty dollars a month, put in consistently, does two things — builds real savings over time, and trains you to think like someone who invests instead of someone who spends. That shift matters more than the actual dollar amount for a long time.
A classmate of mine started putting $15 a month into an index fund during her sophomore year, mostly because a friend nagged her into it. She wasn’t tracking the market or reading finance blogs; she just set it up once and forgot about it. By senior year, the balance wasn’t life-changing, but it was real money that existed only because she started three years earlier than most people her age even think about it. That’s really the whole argument for starting small and starting now instead of waiting for a bigger paycheck that may or may not show up on schedule.
(This is general financial education, not personalised investment advice. Do your own research, or talk to a licensed financial advisor before investing.)
Common mistakes students make with money
A few traps that catch even well-meaning students. Treating a financial aid refund as extra cash when it’s actually borrowed money due back eventually. Letting subscriptions renew quietly month after month. Waiting for a higher income before saving anything at all. Skipping budgeting apps because they seem like a hassle, when most take under five minutes a week once you’re used to them. Splitting every group bill evenly even when it doesn’t match what people actually ordered.
Spotting these patterns early is worth more than any app.
A friend of mine treated her whole first refund check like a bonus and put half of it toward a weekend trip. She wasn’t being irresponsible exactly; she just hadn’t connected the dots that the money was a loan she’d be paying back with interest two years after graduation. That’s the kind of mistake that isn’t really about being bad with money. It’s about nobody explaining how the system actually works before you’re dropped into it.
How to start this week
Pick one, not all seven at once.
- Log every purchase for 7 days.
- Open a separate savings account, even with $20
- Write down three skills you could turn into a side hustle.
- Check if your subscriptions are still worth it.
- Ask about a student discount next time you buy something.
- If you have a credit card, check the balance and plan to pay it off this month.
A small habit you actually keep beats a perfect plan you never start.
Key takeaways
Habits from college tend to follow you into adulthood. Tracking spending for a month reveals patterns most students never notice on their own. A $500 fund covers most common emergencies without wrecking a semester. Flexible side hustles let students earn around a class schedule instead of fighting it. Discounts and used textbooks save real money over four years for almost no effort. Credit cards build credit only when you pay the balance in full each month. Investing small amounts early takes advantage of time, which is arguably the biggest financial asset a college student has.
Frequently asked questions
How much should a college student save each month?
No single number fits everyone, since incomes vary widely among students. A reasonable target is 10 to 20 per cent of whatever you bring in, whether that’s a part-time job, an allowance, or a side hustle. Showing up consistently matters more than the exact figure.
Does a credit card in college actually build credit?
Yes, if you use it carefully. Small purchases paid off in full and on time every month build credit history early. Missing payments or maxing out the limit can hurt your score quickly.
What side hustles fit around a busy class schedule?
Digital ones tend to work best — online tutoring, freelance writing or editing, running social media for a small business, or task-based gig apps. All of these let you work around exams instead of a fixed shift.
Is it realistic to invest with very little money?
Yes. Most apps in 2026 allow fractional shares starting around $5, so you can start with diversified funds like ETFs without needing a big amount up front.
What’s the fastest way to find money I’m wasting without noticing?
Track every expense for 30 days without judging yourself too hard. Most students find one recurring thing — delivery food, a forgotten subscription, coffee — that adds up to more than expected by month’s end.
Should I pay off debt or save first?
It usually helps to build a small starter fund first, even $300 to $500, so a surprise cost doesn’t send you back into debt. After that, focus on high-interest debt like credit cards before putting extra money toward savings or investing.
Is a part-time on-campus job better than a freelance side hustle?
It depends on what you need more of. On-campus jobs tend to offer steadier hours and are usually easier to fit around a class schedule since the employer already understands student life. Freelance work can pay more per hour, but the income is less predictable week to week, especially when you’re just starting out and still building a client base or reputation on a platform.
Final thoughts
None of this is about cutting out everything fun or living broke for four years. It’s about making money decisions on purpose, not by accident. Track spending, keep a small safety net, use the discounts you’re probably already eligible for, and let time work for you by starting to invest early, even in small amounts.
Pick one habit from this list and start it this week. The version of you signing an apartment lease or negotiating a first salary in a few years will be glad you did.
This article is for general educational purposes only and isn’t personalised financial, legal, or investment advice. Individual situations vary, so talk to a licensed financial advisor about anything specific to your circumstances.
About the author: Mehul Patel writes about personal finance, budgeting, and practical money habits for students and young adults, with a focus on simple, actionable advice over financial jargon.